G
Growth
Labor, production, earnings, consumption, and the distribution of economic strength.
Is activity accelerating, resilient, slowing, or breaking?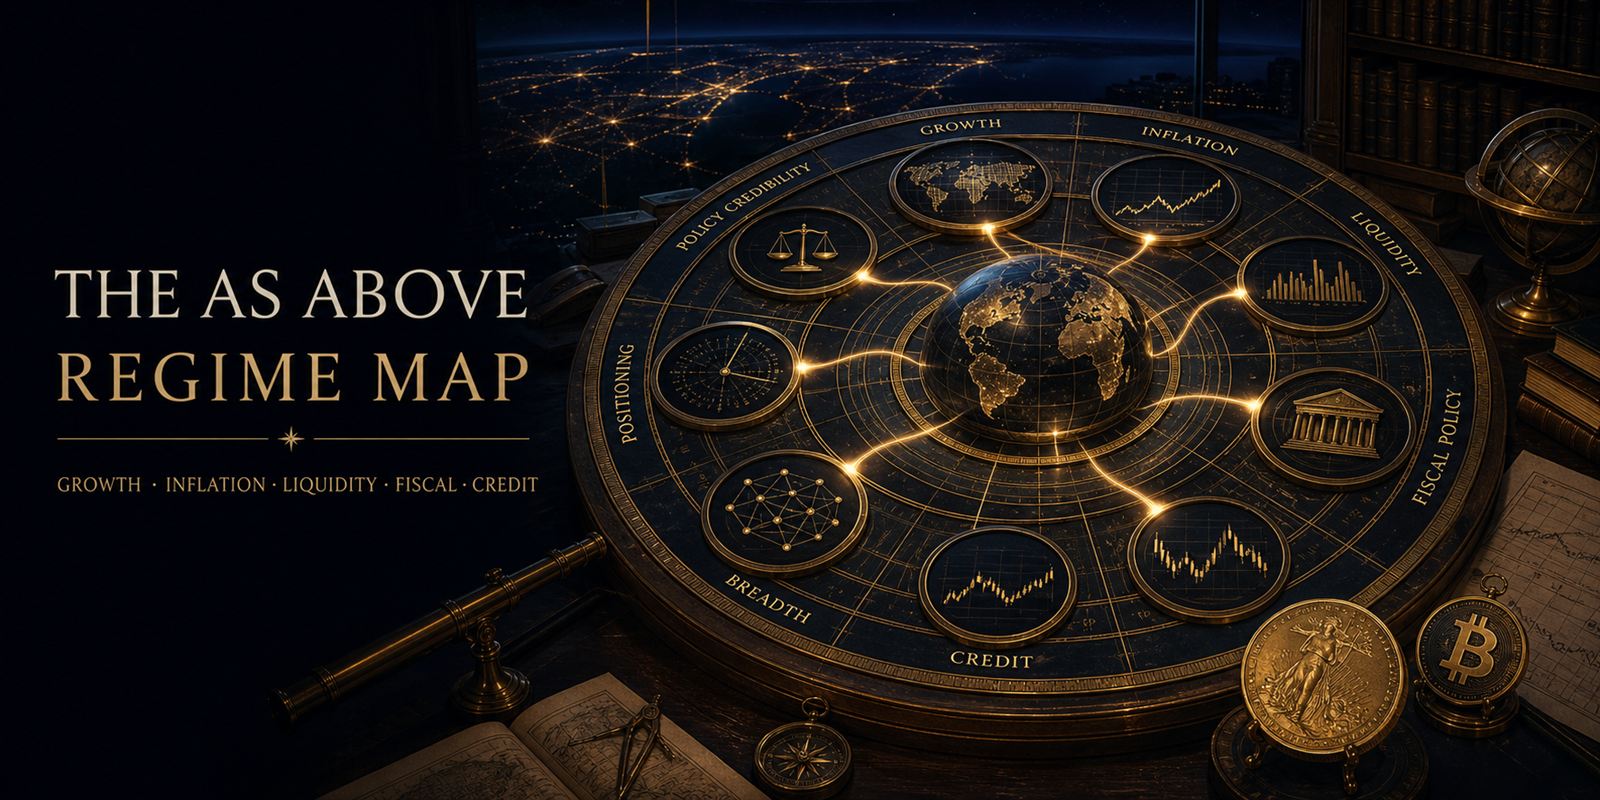
The As Above Intelligence System separates signal from narrative, maps the forces moving capital, and translates changing regimes into decisions with explicit evidence, scenarios, and invalidation conditions.
Markets do not produce one message. They produce a field of competing prices. The edge comes from understanding which relationship is changing first.
The system is designed as a chain of evidence. Raw conditions become relationships; relationships become regime hypotheses; hypotheses become scenarios; scenarios become monitored decisions. Every conclusion remains conditional and revisable.
Timely, source-linked intelligence identifies consequential changes before they harden into consensus.
Eight lenses organize the economic, financial, and policy forces that set cross-asset gravity.
Enduring macro frameworks explain why the relationships matter across cycles and portfolios.
Mind, body, spirit, technology, markets, and natural law reveal the same patterns at different scales.
Scenario trees, invalidation rules, and risk constraints turn interpretation into disciplined action.
No single indicator defines a regime. The map tracks interacting forces and focuses on direction, rate of change, divergence, and transmission across markets.
Labor, production, earnings, consumption, and the distribution of economic strength.
Is activity accelerating, resilient, slowing, or breaking?Headline, core, wages, shelter, commodities, expectations, and inflation breadth.
Is pricing pressure falling, sticky, or returning?Central-bank balance sheets, reserves, collateral, dollar funding, and financial conditions.
Is marginal liquidity entering or leaving the system?Deficits, issuance, maturity, interest expense, Treasury operations, and fiscal impulse.
Is the sovereign balance sheet supporting growth or repricing duration?Spreads, lending standards, defaults, refinancing pressure, and market functioning.
Is the financing channel transmitting stress?Participation across capitalization, sectors, equal weight, cyclicals, and global markets.
Is the tape broadening or hiding behind a narrow index?Leverage, flows, volatility, dealer exposure, sentiment, and crowded consensus trades.
Is price confirming fundamentals or unwinding positioning?Policy reaction functions, real rates, currency behavior, gold, and institutional trust.
Does the market believe the regime can sustain its promises?Positive activity and persistent headline price pressure coexist with substantial Treasury financing needs. This supports conditional portfolio defense, not a declaration that recession is impossible, bonds are broken or fiscal dominance is established.
Reviewed · Next review due
Q2 real GDP grew 1.5% annualized; private domestic final sales grew 4.2%. August payrolls rose 162,000 with unemployment at 4.1%. Headline GDP slowed from Q1, but demand and employment do not establish a recession.
BEA: Q2 GDP, second estimate · BLS: August Employment Situation
Headline CPI was 3.4% year over year, unchanged from July. Core CPI eased from 2.5% to 2.4%. Headline pressure does not mean every component is reaccelerating. CPI is not the Fed's PCE target measure.
The July 29 Fed statement maintained a 3.50–3.75% target range and an ample-reserves policy. That is context, not a fresh liquidity measurement. No synchronized reserves, Treasury cash and funding-rate panel was verified.
Treasury's August 3 estimates project $739 billion of privately held net marketable borrowing in Q3 and $628 billion in Q4. These are forecasts, not completed issuance or proof of a current yield breakout. August yield quotes are retired from the current map.
ICE BofA US high-yield OAS, reported by FRED, was 2.65%, versus 2.70% on September 10: a 5-basis-point narrowing. This does not confirm an immediate spread shock. One day cannot establish a durable trend or rule out refinancing stress.
The August small-cap leadership claim is not treated as current. No same-window equal-weight, small-cap and capitalization-weighted comparison was verified for this review.
The old Bitcoin liquidation narrative does not describe the current book. Fresh positioning, leverage and flows have not been reconciled; no current squeeze or crowded-long claim is made.
Financing needs and inflation-constrained policy pose an adjustment question; they do not prove financial repression or lost credibility. Gold insurance and Bitcoin liquidity sensitivity remain framework judgments, not verified current relative-price signals.
Federal Reserve: July 29 FOMC statement · Treasury: Marketable Borrowing Estimates
Latest macro synthesis: separate liquidity, recession defense, inflation resilience and monetary scarcity.
Earlier framework, not a current price update: monetary scarcity does not make assets interchangeable.
Companion research connects bottlenecks and verified deployment economics to capital. It does not automatically change the macro regime.
The durable framework behind the dated readout.
Treating stocks, bonds, gold, and Bitcoin as substitutes destroys information. Each market prices a different claim, and their divergences often reveal more than their absolute direction.
| Market | Primary claim | What strengthens it | What breaks the thesis |
|---|---|---|---|
| Equities | Productive cash flows and nominal earnings | Earnings growth, open credit, broad participation, and productivity | Yield pressure exceeding earnings growth; widening credit stress |
| Treasuries | Maturity-specific protection: short bills and long duration do different jobs | Disinflationary growth shocks can support long duration; short bills preserve near-term liquidity | Persistent issuance pressure, inflation risk, or rising term premium |
| Gold | Insurance against policy and monetary credibility | Fiscal doubt, reserve diversification, repression risk, currency distrust | Improving credibility and sustained real-return alternatives may weaken the insurance case; forced selling can still cause losses |
| Bitcoin | Convex optionality on liquidity and a scarce monetary network | Expanding liquidity, adoption, reflexive flows, declining dollar scarcity | Deleveraging, dollar shortage, regulatory shock, or failure versus high-beta technology |
The system does not pretend to know one future. It defines the plausible paths, the cross-asset consequences, and the observations that would move probability from one path to another.
If growth holds and inflation cools, earnings and open credit could support equities. Long bonds could also recover as inflation risk falls. Bitcoin participation and gold weakness are possibilities, not necessary outcomes.
Confirm with: breadth, stable spreads, durable earnings revisions.If long yields rise without better growth, both equity valuations and duration could suffer. Gold may offer a different exposure, but neither gold nor Bitcoin is guaranteed protection.
Confirm with: weaker growth, higher long yields, gold strength.If authorities ease funding stress, risk assets may benefit. Bitcoin's sensitivity to liquidity also increases its downside in a reversal. Verify the intervention and its transmission before assuming a rally.
Confirm with: easing funding conditions and Bitcoin strength versus Nasdaq.If labor and credit weaken sharply, equities and Bitcoin may face deleveraging. Long Treasuries can provide defense if inflation recedes. If inflation persists, that familiar hedge may disappoint.
Confirm with: widening spreads, falling breadth, abrupt labor deterioration.Authority is not certainty. As Above earns trust by showing the sources, assumptions, competing explanations, and conditions that would make a thesis wrong.
Policy statements, minutes, official economic releases, market data, filings, and original research precede commentary.
The system emphasizes cross-asset confirmation, divergence, rate of change, and transmission rather than isolated price moves.
Each major publication states what would invalidate its interpretation and records meaningful corrections or revisions.
Every material regime revision will preserve the prior view, the evidence that changed it, and a machine-readable snapshot. The archive makes the evolution of judgment inspectable instead of silently rewriting history.
The existing Sunday editorial review now includes the Regime Map. Each new Signal is checked for a material regime impact. A review can reaffirm the map, revise it or leave an explicit evidence gap; a new article does not automatically imply a new regime.
Fast, source-linked interpretation when a development materially changes the map.
Reopen evidence, identify missing observations, review new Signals and prepare changes for the existing publication process.
A substantial report with data, scenarios, portfolio implications, and monitoring rules.
A defining publication designed to become part of the permanent Oikos canon.
Join The Signal for source-linked intelligence on liquidity, market regimes, Bitcoin, gold, technology, and the forces shaping capital.
For research and educational purposes only. Nothing published by As Above is individualized investment advice or a recommendation to buy or sell any asset.